Does Rental Reimbursement End If My Car Repair Is Delayed by Backordered Parts?
By ChaCha InsurancePublished 13 min read
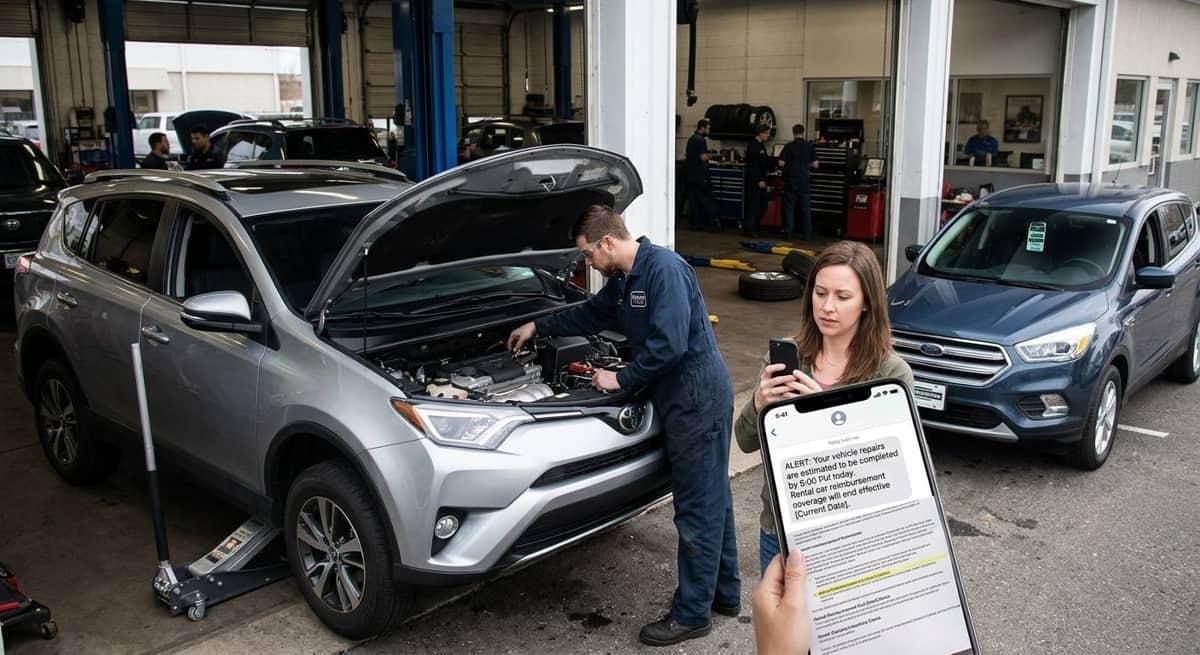
Your car is in the shop, and you just got a call: the part you need is backordered. Nobody can say when it will arrive. The rental car is sitting in your driveway, and one question keeps running through your mind: how long will my insurance keep paying for this?
On this page (10 sections)
Rental reimbursement usually ends when your car is repaired or when you hit your daily or total limit, whichever comes first. A parts delay doesn't pause that clock, but how your policy defines the repair period can matter. Check your declarations page and policy wording.
Does a Backorder End Your Rental Coverage?
A backorder doesn't usually end your rental coverage on its own. But it usually doesn't extend it either. Your rental benefit generally stops at one of three points:
- Your repair is finished. Once your car is fixed and drivable, the benefit typically ends, even if you haven't picked it up yet.
- You reach your limit. That could be a daily dollar limit, a total dollar limit, or a set number of days.
- Your claim is settled as a total loss. If the insurer decides your car isn't worth repairing, rental coverage often ends once they make a settlement offer based on your car's actual cash value minus your deductible.
So a part delay doesn't flip a switch. Your coverage keeps running, but only up to your limits. If the wait outlasts those limits, the extra rental days may come out of your pocket.
Many policies also tie rental coverage to a "reasonable" repair time, which is why the exact wording of your policy matters. What counts as reasonable can depend on the facts of your claim, and we'll look at that in a moment.
How Rental Reimbursement Coverage Works
Rental reimbursement is an optional add-on to your personal auto insurance. You choose it, and you pay a little extra for it. It usually applies when your car is being repaired after a covered collision or comprehensive claim. If your car is in the shop for routine maintenance or a repair that isn't part of a covered claim, it generally won't apply.
Look at Your declarations page, the summary page that lists your types of insurance coverage and limits , the summary page at the front of your policy. The wording varies, but you may see something like "Car Rental Expense, Each Day / Each Loss." The "each day" number is the most the insurer will pay for one day of rental. The "each loss" number is the most it will pay for the whole claim. State Farm explains this setup on its rental services page, and most insurers do it in a similar way.
There are usually two ways:
- Direct billing: The insurer pays the rental company directly. You cover anything above your daily limit.
- Pay and submit receipts: You pay the rental company first, then send your receipts to the insurer for reimbursement.
Most policies cover a rental that is comparable to your own car. Some also allow rideshare, taxi, or public transit costs, but you'd still need to stay within your limits.
What it usually doesn't cover. Common exclusions include:
- Upgrades to a bigger or fancier vehicle than yours
- Extra insurance the rental company offers at the counter
- Fuel
- Mechanical breakdowns
- Repairs unrelated to a covered claim
Limits vary a lot between insurers and between policies. The Insurance Information Institute has described ranges from about $25 per day with a $750 maximum to $100 per day with a $3,000 maximum. Those are general ranges, not a quote. Your own numbers could be higher, lower, or structured differently, so check your own paperwork.
How Daily and Total Limits Interact
This is where most surprises happen. Your policy usually has two limits working at the same time, and either one can end your coverage.
The insurer pays the lesser of your actual rental cost or your daily limit. Payments stop once the total maximum is used up.
Here's a simple way to figure out how many days your coverage could last:
Total limit ÷ daily limit = maximum covered days
For example, $1,200 ÷ $40 = 30 days.
Let's walk through four examples. These are illustrations, not quotes, and your policy may work differently.
Example 1: The rental fits under the daily limit. Your policy pays up to $40 a day, with a $1,200 total. Your rental costs $40 a day. The insurer pays the full cost, and your coverage lasts 30 days.
Example 2: The rental costs more than the daily limit. Same policy, but your rental costs $55 a day. The insurer pays $40 and you pay $15 each day. Your coverage still runs out after 30 days, because the total limit is based on what the insurer pays, not what the rental costs. Over 30 days, you'd pay $450 yourself, even though your coverage hasn't "ended" yet.
Example 3: A longer delay. Your policy pays up to $30 a day, with a $900 total. That's 30 days of coverage. Your part is backordered, and the repair takes 40 days. Days 31 through 40 are no longer covered. If your rental costs $42 a day, those 10 days come to $420 out of your pocket.
Example 4: A day limit and a dollar limit together. Some policies set both. Say yours pays up to $50 a day, with a $1,500 total, but also caps the benefit at 20 days. Twenty days at $50 is $1,000, so the 20-day limit ends your coverage before you reach the $1,500. Whichever limit is lower controls.
| Example | Daily limit | Total limit | Rental price | Your out-of-pocket per day | Days until the cap |
| 1 | $40 | $1,200 | $40 | $0 | 30 |
| 2 | $40 | $1,200 | $55 | $15 | 30 |
| 3 | $30 | $900 | $42 | $12 | 30 |
| 4 | $50 | $1,500 (20-day cap) | $50 | $0 | 20 |
Note: In Example 3, you pay $12 a day (the $42 rental minus the $30 limit) during the covered days, and the full $42 after day 30.
Coverage generally ends when your car is repaired, not when you pick it up. If your car is ready on Friday and you don't collect it until Monday, you could be paying for the weekend yourself. If you can, pick up your car as soon as it's ready.
What Your Policy Says About Repair Delays
If you want to know how your own policy treats delays, go to the source. Here's what to open and what to look for.
Documents to find:
- Your declarations page
- The full policy form
- The section on rental, "transportation expense," or "loss of use"
Phrases to look for. Policies are worded differently, so these are ideas, not exact quotes:
- "Reasonable time" to repair. Many policies tie coverage to the time reasonably needed to complete repairs.
- A maximum number of days. Some policies cap coverage at a set number of days, such as 30.
- When coverage "ends." Look for wording that says what stops the benefit: repair complete, settlement offered, or limit reached.
- Total loss rules. These explain what happens to your rental if the car isn't repaired.
- How delays are treated. Some policies, or some insurers' claim practices, may treat a parts shortage differently from a repair shop's scheduling backlog.
Policies often say your rental should last as long as it reasonably takes to repair the car. That's a flexible phrase. Some sources note that a documented parts delay may be considered part of the repair period, depending on the situation. But that isn't a guarantee. Whether a delay counts as reasonable can depend on your policy wording, your state's rules, and the facts of your claim.
Even when a delay isn't your fault, your dollar and day limits still apply unless your insurer decides otherwise. A good reason for the delay doesn't automatically raise your limit.
Insurers can handle delays differently, and state regulations vary. If you have questions or concerns about how your claim is being handled, your state's department of insurance can explain your rights and how to file a complaint. You can find yours through the NAIC state insurance department directory or by searching "[your state] department of insurance."
Why Backorders Drain Your Rental Limit Faster Than People Expect
Many people assume the repair itself is what takes so long. Often, the waiting is the bigger part. Here's what a typical delayed claim can look like:
- You report the claim.
- The shop writes an estimate.
- The shop takes your car apart (the "teardown") and often finds more damage that wasn't visible at first.
- The insurer reviews the added damage and approves it.
- The shop orders parts.
- A part is backordered.
- The shop schedules the repair once the parts arrive, and it may need to wait for an open spot.
- You pick up your car.
The Insurance Information Institute has noted that the average vehicle repair takes about two weeks, which is why 30 days of coverage is common and usually enough. But with a backorder, the rental clock can start on day one while the actual work doesn't begin until weeks later.
A shop often won't order all the parts until the car has been taken apart and every damaged piece is found. So a repair that takes four days of hands-on work can still eat 15 or 20 days of your rental while everyone waits on approvals and deliveries.
Say your car goes into the shop on day 1. The teardown happens on day 4. Added damage is approved on day 9. The parts are ordered on day 10, but one is backordered for two weeks. It arrives on day 24, and the repair is finished on day 28. Under a 30-day limit, you're almost out of coverage, and nothing went wrong on your end.
Not every delay is the same. A delay while you wait for the shop to order parts is different from a delay while you wait for the insurer to approve something. Either one is worth writing down, with dates, because it helps you explain what happened if you need to ask questions later.
Sample Rental Expense Tracker
A simple tracker lets you see your limit running down in real time. It also gives you a clean record to share with your adjuster if you have questions. Here's an example using a $40 daily limit, a $1,200 total, and a rental that costs $48 a day:
| Date | Days used | Daily rental charge | Daily limit | Covered amount | Your out-of-pocket | Running total paid by insurer | Remaining total limit | Notes (contact, reference #) |
| Nov 1 | 1 | $48 | $40 | $40 | $8 | $40 | $1,160 | Picked up rental, claim # added |
| Nov 2 | 2 | $48 | $40 | $40 | $8 | $80 | $1,120 | Shop confirmed teardown |
| Nov 3 | 3 | $48 | $40 | $40 | $8 | $120 | $1,080 | Parts ETA: "2–3 weeks" (told by shop) |
Tips for using your tracker:
- Log every day, including weekends and holidays.
- Keep every receipt, especially if your policy is pay-and-submit.
- Write down who said what and when. Note names, dates, and any reference numbers.
- Update the parts ETA each time the shop changes it.
A copy-and-paste version of this table works well in a spreadsheet. Add a formula for the "Remaining total limit" column, and it'll update itself.
This tracker is a personal record. It does not extend your coverage or guarantee reimbursement.
What to Do If a Parts Delay Is Eating Your Rental Limit
You can't make a part arrive faster, but you can stay informed and keep a clear paper trail. Here are steps worth taking:
- Check your limits now. Look at your declarations page before the delay grows.
- Ask the shop for a written ETA, and ask them to let you know if it changes.
- Tell your adjuster about the delay in writing. Ask how your policy treats it.
- Ask if your policy has any provision for extended repair periods. Don't assume one exists, and don't be surprised if it doesn't.
- Ask how and when you'll be notified as you get close to your limit.
- Keep your tracker and receipts up to date.
- Ask if the shop can find an alternative or aftermarket part. If so, find out how that might affect the repair, your warranty, and your costs before you agree.
- If you disagree with a decision, ask for the reasoning in writing, and learn what consumer complaint options your state insurance department offers.
An honest note: your insurer may or may not agree to anything beyond your limits. None of these steps guarantee an extension. But they make sure you're informed and organized, which helps you make good decisions.
Options If Your Rental Limit Runs Out Before the Repair Is Done
If your coverage ends before your car is ready, you still have choices:
- Pay the difference at a lower daily rate. Ask the rental company if a cheaper vehicle class or a longer-term rate is available.
- Switch to a smaller car. You might not need the same size you've been driving.
- Use rideshare or public transit for some trips.
- Borrow a car from family or a friend, if that works for you and the vehicle is properly insured.
If another driver caused the accident, their insurer's liability coverage may handle loss of use differently than your own policy. It's worth asking your adjuster whether that applies to you.
For the future, your rental limits are best reviewed when your policy renews, or if you decide to switch auto insurance to a new company. Higher limits usually cost more in premium, so it comes down to weighing the cost against how much a long repair would disrupt your life.
The Bottom Line
A backordered part can make a short repair feel endless, and your rental benefit doesn't stretch just because the wait does. Your limits are what usually control things. The wording in your policy about repair time can also matter. And keeping good records helps you understand your position at every stage.
This article is general education. It isn't legal advice, and it isn't a decision about your specific coverage. For answers about your own policy, read it closely and talk to your insurer or a licensed agent.
If you'd like help reviewing whether your rental limits fit your life, a licensed professional can walk through your options with you. There's no pressure, and no one can promise you a price without looking at your details.
How ChaCha Insurance can help
ChaCha Insurance is an independent insurance agency based in Chatsworth, California. Tell us what you need covered and we will compare quotes from the insurance companies we work with, free.
Coverage in this guide
Frequently Asked Questions
Does rental reimbursement end if my car is waiting on parts?
Not automatically. Coverage typically continues until the repair is done or you reach your limit. A parts delay doesn't pause the clock, so a long wait can use up your coverage. Your policy wording on "reasonable" repair time may matter.
Does the 30-day limit start when I pick up the rental or when the claim opens?
It depends on your policy. Many tie the benefit to the period your car is being repaired, and some count days from when you start using the rental. Check your policy language, or ask your adjuster to explain how your days are counted.
What if the rental costs more than my daily limit?
You pay the difference. If your limit is $40 a day and the rental is $55, you cover $15 daily. Your total limit also drains by the amount the insurer pays, so the extra cost doesn't stretch your coverage.
Does a total loss end rental coverage differently?
Often, yes. If your car is declared a total loss, rental coverage commonly ends once the insurer makes a settlement offer, even if you haven't bought a replacement yet. Policies differ, so confirm the details with your adjuster.
Can I use rideshare instead of a rental to stretch my limit?
Some policies allow rideshare, taxi, or public transit costs to count toward your benefit, but you'd still stay within your daily and total limits. Using cheaper options on some days may let your total last longer. Ask your insurer first.