Scheduled Jewelry Coverage vs a Higher Blanket Limit for an Engagement Ring: What Changes?
By ChaCha InsurancePublished 10 min read
You have the ring. Now you want to know it's protected. Here's the short version: raising your policy's jewelry limit (often called a "blanket" increase) gives you a bigger dollar cap, but the policy still covers the same causes of loss and still charges the same deductible. Scheduling the ring changes the kind of coverage you have, not just the amount.
On this page (11 sections)
"Blanket limit" isn't an official insurance term. It's how many people describe raising the cap on all their jewelry at once, without listing each piece. This guide is for engaged and newly married readers in the U.S. whose ring is worth more than their policy's jewelry theft limit. We'll walk through how each option pays, what it costs you at claim time, what it covers, and what paperwork you'll need.
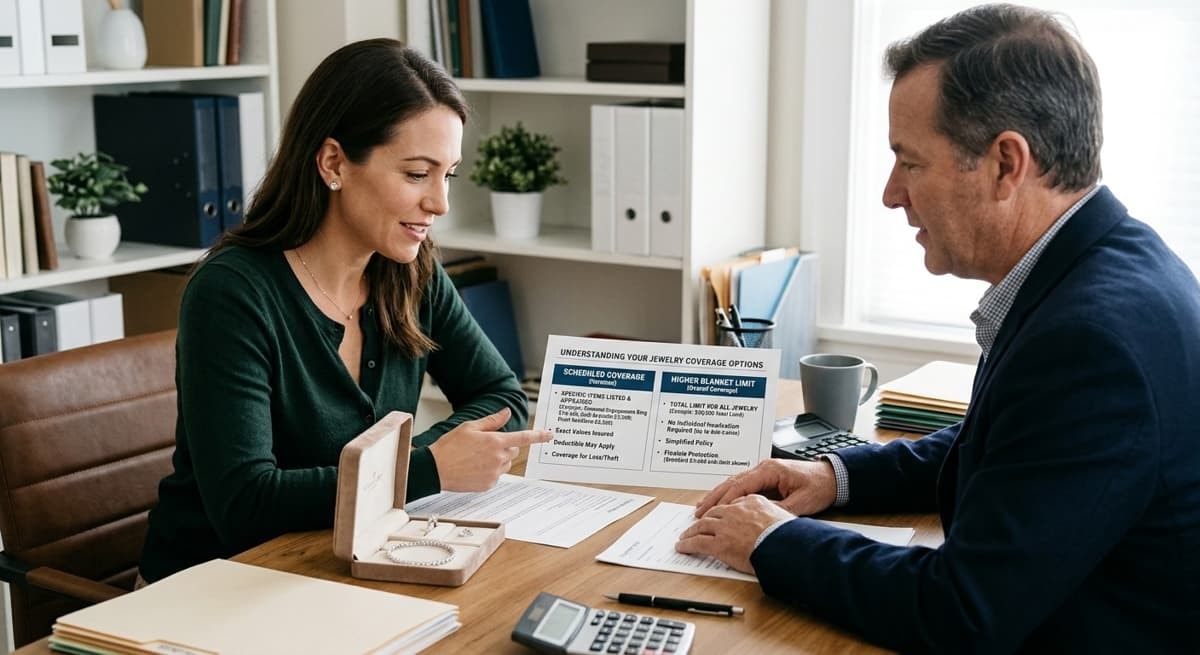
Scheduled jewelry vs a blanket limit
If you only remember one thing, remember this: a higher blanket limit makes the cap bigger. Scheduling makes the protection broader.
| Higher blanket limit | Scheduled ring | |
| How it works | Raises the policy's jewelry cap for all jewelry | Lists your ring by name and value |
| What's covered | Same named causes as your regular policy | Broad coverage, including loss and accidental damage |
| Deductible | Your regular deductible applies | Often none, though some insurers add one |
| Payout basis | Usually your policy's standard basis | Based on the ring's listed value, with insurer options |
| Per-item cap | Often yes | Up to the amount you schedule |
| Appraisal | Usually not needed up front | Often needed, depending on value and insurer |
| Effect on your home policy | A claim counts as a home policy claim | May sit on its own policy or endorsement |
Choose a blanket increase if your ring is only slightly above your current limit and you mainly worry about theft or fire.
Choose scheduling if you want protection when the ring is lost, slips down a drain, or loses a stone, and you'd like to avoid paying your home deductible.
How a standard homeowners or renters policy treats an engagement ring
Most people assume their homeowners insurance or renters policy covers their belongings up to the full amount of their personal property coverage. . For jewelry, that's not quite true.
Standard policies put a lower "special limit on jewelry", and that cap applies specifically to theft.
The cap applies to theft, and the amount depends on the policy form. One recent version of the standard ISO homeowners form lists $2,000 for theft of jewelry and furs, while another industry form lists $2,500. Older forms and many study guides still show $1,500. Your own policy may differ, so check your homeowners declarations page or ask your agent.
Two more things matter here. First, personal property is usually covered only for a list of named causes, such as fire, theft, and certain kinds of storm damage. If something isn't on the list, it isn't covered. Second, your regular deductible applies.
Here's what that looks like. Say your ring is worth $9,000 and your policy's theft cap for jewelry is $2,000. If the ring is stolen, the most you can get is $2,000, minus your deductible. That's a big gap, and it's the reason people start looking at their options.
What a "higher blanket limit" is and what it doesn't change
On many homeowners policies, you can add an endorsement that raises the special limits. On the standard ISO forms, this is the "Coverage C Increased Special Limits of Liability" endorsement (HO 04 65). Some insurers use their own name for it.
It does one main thing: it raises the dollar amount your policy will pay for jewelry theft. It does not change what is covered. If your policy only covers named causes, those are still the only causes. If your regular deductible applies, it still applies. And on the standard ISO form, there's a cap on each item, so one expensive ring may not get the full increase. An older edition of that endorsement reportedly capped each item at $1,000, so it's worth reading the current wording closely.
There's another quiet limit. Raising the jewelry cap doesn't add new personal property coverage to your policy. A large jewelry claim still comes out of the same overall pot that covers everything else you own.
A word of caution about the term itself. Some insurers use "blanket" for different products, such as an unlisted jewelry floater with a per-item limit. Before you buy, ask exactly what the coverage is called, what the per-item cap is, and what causes of loss it covers.
What scheduling an engagement ring changes
Scheduling means you list the ring, with a description and a value, either as an endorsement on your home policy (HO 04 61 on the standard ISO form) or on a separate personal articles or jewelry policy.
The biggest change is the type of coverage. Scheduled jewelry is generally covered for "open perils," which means it's covered unless the policy specifically excludes the cause. In practice, that includes things a regular policy often doesn't, like the ring slipping off your finger and disappearing, or going down the garbage disposal. On the standard ISO scheduled form, the main exclusions are wear and tear, gradual deterioration, insects or vermin, war, and nuclear hazard. Flood and earthquake damage, which regular home policies typically exclude, are generally covered on scheduled jewelry.
Scheduling also often includes help for new purchases. If you already schedule jewelry and then buy a new piece, the standard form covers it for a limited time, up to the lesser of 25 percent of the amount you've scheduled for that class or $10,000. You'll need to tell the insurer within 30 days and pay any added premium.
Some insurers ask for extra steps with high-value rings, such as keeping the ring in a vault when you're not wearing it, or having an alarm system at home. If you agree to those, you may get a lower rate. If you don't follow them, a claim could be reduced or denied, so ask what's required.
Valuation: how a loss is actually paid
This is the part people often miss, and it affects what you'll really receive.
With a blanket increase, the loss is settled the way your policy normally settles personal property. That's usually actual cash value, which is replacement cost minus depreciation, unless your policy has a replacement-cost endorsement. For a diamond that holds its value, depreciation may not be large, but it can still lead to arguments about what the ring was worth.
With a scheduled ring, the amount you list is the most the insurer will pay. It's not always the amount you'll receive. On the standard ISO scheduled form, the insurer can pay the least of the ring's actual cash value, the cost to repair or replace it, or the amount of insurance. And the insurer may choose to replace the ring itself instead of sending you a check, sometimes buying it at a lower price than you'd expect. Some insurers do offer "agreed value" coverage, where you and the insurer agree on the value up front, so ask if that's available.
Three tips follow from this:
- Don't under-insure to save on premium. If you list the ring for less than it's worth, you may be left short after a loss.
- Understand the pair-or-set rule. If you lose one earring, the insurer may only owe the difference in value, not a brand-new pair.
- If your ring is a particular brand, ask whether the insurer replaces with "like kind and quality."
Deductibles and claim impact
With a blanket increase, your regular homeowners deductible applies. If your deductible is $1,000 and the ring is stolen, you pay the first $1,000 yourself.
With a scheduled ring, the standard ISO form typically has no deductible on scheduled items. That said, insurers can add one, particularly on larger schedules. Don't assume. Look at the policy or ask for it in writing.
There's one more thing to think about: what a claim does to your home policy. Jewelers Mutual, a jewelry specialist, has said a jewelry claim on a homeowners policy could affect the whole policy. That could mean a higher premium or trouble at renewal. A separate jewelry policy can keep the ring's claim history apart from your house.
Covered causes: the situations people actually worry about
Here's how the two options often compare in real life. Remember that wording varies by insurer, so treat this as a general guide.
| What happens | Blanket increase | Scheduled ring |
| Stolen from your home | Usually covered, up to the higher cap | Covered |
| Stolen from your car | Depends on policy terms and cap | Covered |
| Lost at the gym or while traveling | Often not covered | Generally covered |
| Slips down the drain | Often not covered | Generally covered |
| Stone falls out of the setting | Often not covered | Often covered, but check the wording |
| Fire | Usually covered | Covered |
| Flood or earthquake | Often excluded | Generally covered |
Fire and theft are usually covered either way. The real difference shows up with the "oops" moments: losing the ring, dropping it, or watching a stone go missing. Those are the situations that happen most often to rings people wear every day. Normal wear and tear, like a prong slowly wearing down, usually isn't covered under either option.
Appraisal and documentation requirements
With a blanket increase, you generally don't need a new appraisal to buy the endorsement. But at claim time, you'll need proof that you owned the ring and what it was worth, such as the receipt, certificate, and photos.
With a scheduled ring, the insurer decides when an appraisal is needed, and the rules vary. Here are some examples. Acuity suggests scheduling pieces worth more than $5,000 and typically asks for a jeweler's appraisal above $20,000. USAA's scheduled policy applies to an item over $2,500 or a collection over $10,000, and may ask for an appraisal depending on value. Chubb's Masterpiece program requires appraisals at $100,000 and above. These are examples, not rules, so check with the insurer you're considering.
A good appraisal usually includes:
- A clear description of the ring, including metal type and weight
- The diamond or gemstone details: cut, color, clarity, and carat weight
- Any treatments, such as laser clarity enhancement or color treatment
- Measurements and clear photos
- The replacement value, not what you paid
- A signature from a credentialed appraiser, such as a certified gemologist (GIA and AGS are two well-known credentials)
Two extra tips. If your stone was bought abroad, having it re-appraised in the U.S. can prevent disagreements later. And plan to update the appraisal every few years, since jewelry prices change and an old value can leave you underinsured.
Which one fits your situation?
There's no single right answer, but these examples can help.
- Your ring is just above the cap and you have no other valuables. A blanket increase may be enough, especially if your main worry is theft. Just know that lost or dropped rings may not be covered.
- Your ring costs $15,000 or more. Scheduling is usually worth a close look. The gap between a capped payout and the real value is large, and broader coverage matters more.
- You rent. A renters policy has the same kind of cap, so the same trade-offs apply. Scheduling through a separate jewelry policy is common, and it can stay with you if you move.
- It's an heirloom. Replacing it may be impossible, so agreed value, if offered, deserves attention, along with a good appraisal.
- You travel a lot. Scheduling is generally better, since it typically covers loss and accidents away from home.
The bottom line
A higher blanket limit raises how much you can collect. Scheduling changes what you're covered for, how a loss is paid, and whether you'll owe a deductible. For many engagement rings, especially those worn every day, scheduling closes more of the gaps.
Your next step is simple: get an up-to-date appraisal, contact ChaCha Insurance to compare quotes on both options, and review them side by side in writing.
How ChaCha Insurance can help
ChaCha Insurance is an independent insurance agency based in Chatsworth, California. Tell us what you need covered and we will compare quotes from the insurance companies we work with, free.
Coverage in this guide
Frequently asked questions
Is a rider the same as scheduling?
Usually, yes. People often use "rider," "floater," and "scheduled personal property endorsement" to mean the same thing: a way to list a specific item for its own coverage. The exact name varies by insurer.
Do I need an appraisal?
Not always. Lower-value rings may only need a receipt or description, while higher-value ones usually need an appraisal from a qualified jeweler or gemologist. The threshold depends on the insurer.
Will my premium go up?
Yes, either option costs extra. Scheduled jewelry premiums are often around 1% to 2% of the insured value per year, according to industry reports, but your price depends on your insurer, the ring's value, and where you live.
What if my ring's value changes?
Tell your insurer. If prices rise, your ring may be underinsured. Updating the appraisal every few years and adjusting the coverage helps you avoid a shortfall.